Is the P&C Core Insurance Market Ready for an AI Revolution?
Primary data sourced from NAIC, ACORD, the Geneva Association, AM Best, Verisk, Swiss Re Institute, EIOPA, IRDAI, APRA and MAS, alongside public filings and investor disclosures from Guidewire, Duck Creek, Sapiens and Majesco (2024-2026 publications). TrendX Insights cross-referenced these figures against its own syndicated P&C Core Insurance Market research and multiple independent analyst estimates to give readers a transparent range rather than a single unverifiable number. All figures are in USD unless noted otherwise and are dated through July 2026.
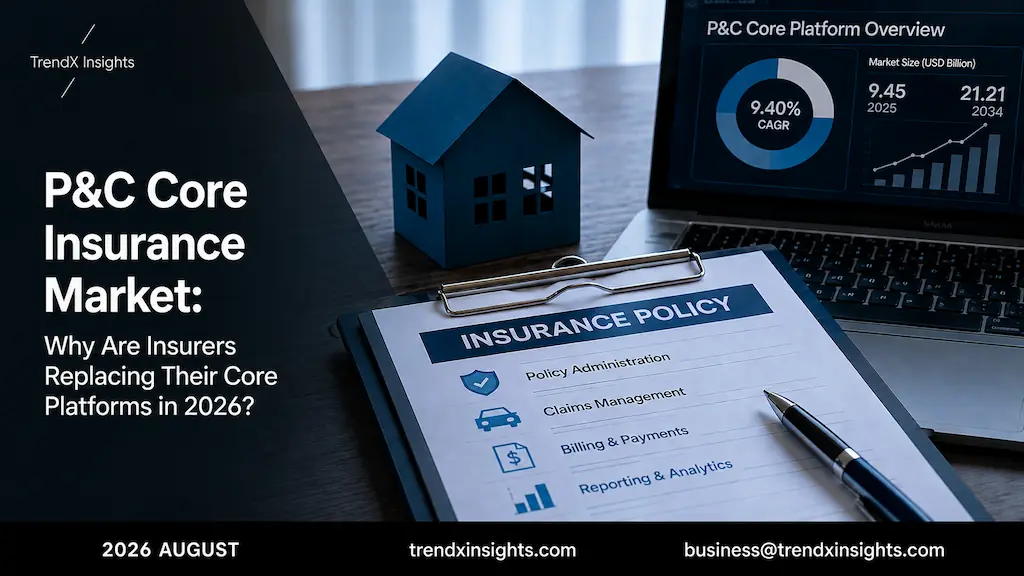
The global Property & Casualty (P&C) core insurance software market reached USD 9.45 billion in 2025 and is projected to expand to USD 21.21 billion by 2034, representing a 9.40% compound annual growth rate (CAGR). Growth is primarily driven by Tier-1 and Tier-2 carrier migrations from legacy mainframe infrastructure (COBOL/AS400) to API-first SaaS platforms. North America currently commands 54.6% of global expenditure, while Asia-Pacific is projected to record the highest regional growth at 14.80% CAGR through 2034. Guidewire, Duck Creek Technologies, Sapiens, and Majesco account for over 60% of enterprise SaaS contracts across policy administration, claims, and billing.
Where Does the P&C Core Platform Market Stand in 2026?
Enterprise technology investments across Property & Casualty insurers are increasingly concentrated on core platform replacements. Global insurance IT expenditure reached USD 227.7 billion in 2025, with core system software and integration services accounting for approximately 18% of total carrier technology budgets. Cloud-native delivery models now represent 82% of all new policy administration system (PAS) selections, compared to 35% in 2019.
Guidewire, Duck Creek Technologies, Sapiens, and Majesco continue to lead the Tier-1 and Tier-2 carrier segments. While 90% of US carriers report active trials with Large Language Models (LLMs), production deployment of artificial intelligence remains concentrated in front-end claims triage and fraud screening. Full end-to-end autonomous claims adjudication is currently limited to 23% of carriers, primarily within standardized personal lines auto and property risk.
What Is a P&C Core Platform?
A P&C core platform comprises the mission-critical software engines that record, calculate, and process carrier transactions across six operational pillars: Policy Administration, Claims Adjudication, Premium Billing, Underwriting Workbenches, Rating/Pricing Engines, and Integration APIs. The platform serves as the single source of truth for policyholder liabilities, earned premium recognition, reserve allocations, and reinsurance cessions.
| Component | Function |
|---|---|
| Policy Administration System (PAS) | Manages the full policy lifecycle: quoting, binding, issuance, endorsements, renewals, cancellations |
| Claims Management System | Handles first notice of loss (FNOL), investigation, adjudication, reserves management, settlement |
| Billing Platform | Manages premium billing, payment processing, commission accounting, receivables |
| Underwriting Workbench | Supports risk evaluation, data enrichment, and decision-making workflows |
| Rating Engine | Calculates premiums based on risk factors, regulatory rules, and pricing models |
| Integration Layer (APIs) | Connects core modules with external systems, data providers, and distribution channels |
Why Core Platforms Matter
The U.S. P&C industry processed USD 976.8 billion in net premiums written in 2025 (+4.6% YoY per NAIC data). Every policy issuance, premium billing cycle, and claim settlement executes through the core platform. Legacy core architectures directly constrain operational efficiency and loss ratios: maintaining legacy mainframes consumes 50% to 80% of total IT budgets at mid-sized carriers, limiting capital allocated to new product development. Data from the 2025 ACORD Digital Maturity Study reveals that only 25% of the 210 largest global carriers have fully digitalized core workflows, creating an operational margin gap of 400 to 600 basis points between digitally mature carriers and legacy peers.
Maintenance of legacy mainframe systems consumes between 50% and 80% of total IT budgets across mid-sized and Tier-1 carriers. The 2025 ACORD Digital Maturity Study indicates that only 25% of the 210 largest global P&C insurers have fully digitalized policy and claims value chains.
Evolution of P&C Insurance Core Systems
The Mainframe Era (1970s to 2004)
First-generation insurance core systems relied on mainframe architectures programmed in COBOL or Fortran, optimized for nighttime batch processing. An estimated 35% to 40% of North American policy administration systems remain tied to legacy mainframe code bases as of 2026.
The On-Premise COTS Era (2005 to 2018)
Commercial-off-the-shelf (COTS) software packages replaced custom-coded mainframes with vendor-supported applications (Guidewire, Duck Creek, Sapiens). Modernization during this period involved multi-year on-premise deployments with total implementation costs ranging from USD 50 million to USD 300 million for enterprise carriers.
The Cloud-Native SaaS Era (2019 to Present)
Current architecture centers on cloud-native, microservices-based SaaS platforms. Over 80% of new core selections specify cloud deployment. Modern platforms utilize microservices, API-first integrations (MACH architecture), and embedded event streaming to enable sub-second rating and real-time claims routing.
Key Components of Modern P&C Core Platforms
When evaluating the top p&c insurance core systems platforms comparison, buyers prioritize six functional modules that define a modern core platform:
Policy Administration Systems
Modern PAS solutions support multi-line, multi-jurisdiction product configuration with real-time rating and rules engines. Leading carriers using modern platforms achieve straight-through processing rates of 70 to 85 percent for standard personal lines policies.
Claims Management Systems
Claims represent the single largest expense category for P&C insurers. Modern claims management systems integrate AI-powered triage (90 to 95 percent accuracy at leading carriers), computer vision for damage assessment, and automated settlement workflows. Digital claims filing reached approximately 55 to 60 percent of new claims at top US carriers in 2024, up from 35 percent in 2021, and average auto claims processing time has fallen from around 30 days in 2018 to 15-20 days among digitally mature carriers.
Billing and Payments
Modern billing platforms support flexible installment schedules, automated commission reconciliations, and real-time digital payment processing, achieving 85% to 95% automated payment matching across standard personal and commercial accounts.
Analytics, AI, and Fraud Detection
According to the Coalition against insurance fraud (CAIF), fraud accounts for an estimated $308.6 billion in losses each year in the United States alone, of which $90-122 billion comes from Property & Casualty (P&C). Real-time risk scoring engines integrated at FNOL detect 40% to 60% more fraudulent filings than legacy rule-based triggers.
Global P&C Insurance Industry Overview
Global P&C premium volume dictates regional TAM for core software vendors. Total non-life premium expenditure reached USD 2.4 trillion in 2024, with North America and Europe representing the largest markets.
| Region | Estimated P&C Premiums | Global Share |
|---|---|---|
| North America | USD 1.81 trillion | 42.05% |
| Europe | USD 1.48 trillion | 34.35% |
| Asia Pacific | USD 946 billion | 22.01% |
| South America | USD 80 billion | 1.86% |
| Middle East and Africa | USD 31 billion | 0.73% |
| Global Total | USD 4.3 trillion | 100% |
P&C Premium Share: North America 42.05% · Europe 34.35% · Asia Pacific 22.01% · South America 1.86% · Middle East and Africa 0.73%
Global non-life premiums are projected to reach approximately USD 4.85 trillion by 2026, driven by rate increases, economic growth, and emerging risk categories such as cyber insurance (which exceeded USD 14 billion in global premiums in 2024) and parametric insurance (estimated at USD 3-4 billion in 2024).
Insurance Penetration Rates by Country and Region
Insurance penetration (premiums written as a percentage of GDP) benchmarks structural market depth. According to OECD 2025 data, non-life penetration ranges from 1.0% in developing markets like India to 3.7% in the United States and over 10% in select European economies.
| Country / Region | Penetration Rate | Basis |
|---|---|---|
| Luxembourg | 33.0% | Total (life + non-life); highest OECD |
| US, UK, France | Above 10% | Total (life + non-life), OECD 2024 |
| OECD average | 6.2% | Total, OECD 2024 (up from 6.0%) |
| All reporting countries | 5.4% | Total, OECD 2024 (up from 5.3%) |
| United States | 3.6-3.7% | Non-life only; TrendX calculation |
| Global non-life avg | 3.9% | Non-life; Swiss Re Institute |
| India | 1.0% | Non-life; well below global average |
| Romania | 1.1% | Total; lowest among reporting countries, 2024 |
Penetration: Luxembourg 33.0% · US/UK/France >10% · OECD 6.2% · Global Non-Life 3.9% · India 1.0%
P&C Premium Growth by Region
| Region / Market | Most Recent Growth | Trend / Forecast |
|---|---|---|
| Global non-life | +4.3% real (2024, decade-high) | +2.3% avg forecast, 2025-2026 |
| United States (P&C) | +5.0% (2025, $1.11T) | Combined ratio 92.9-93.0% |
| Europe (non-life) | +5.8% (2024) | DORA & Solvency II driving upgrades |
| South America | +7.6% (2024) | Insurtech funding up 117% in 2025 |
| Asia Pacific | Fastest-growing globally | 14.80% CAGR through 2034 |
| Global P&C market | USD 2.4 trillion (2024) | Grew faster than GDP past decade |
Why Insurers Are Modernizing Core Platforms
Carrier core replacements are driven by six structural cost and revenue pressures:
- Digital transformation expenditure: U.S. insurance modernization spending reached USD 132.86B in 2024 and is projected to expand to USD 229.07B by 2029, with 74% of CIOs prioritizing core infrastructure.
- AI Model Integration: 76% of U.S. insurers have deployed generative AI in at least one operational division, with full-scale production adoption expanding from 8% in 2024 to 34% in 2025.
- Cloud Architecture Parity: 90% of carriers utilize cloud resources, with cloud SaaS representing over 80% of all new core software selections.
- Digital Self-Service Demands: 70% to 75% of personal lines policyholders utilize digital self-service portals, accounting for 55% of all policyholder interactions.
- Claims Automation Velocity: Straight-through processing (STP) rates for standard auto physical damage claims rose from 8% in 2021 to 31% in mid-2025.
- Regulatory Compliance: Frameworks including DORA (EU), IFRS 17, Solvency II, and NAIC AI governance bulletins require real-time reporting capabilities absent in legacy systems.
Data from J.D. Power’s 2024 Claims Satisfaction Study indicates a 70-point satisfaction differential (880 vs. 810 out of 1,000) between carriers running cloud-native claims portals and those relying on legacy intake channels, directly impacting policyholder renewal rates.
US P&C Industry Financial Performance: 2024 vs 2025
U.S. P&C insurers generated USD 61.2 billion in net underwriting gain in 2025, lowering the net combined ratio to 92.9% (a ten-year operational benchmark). Expanded underwriting margins and a record USD 1.27 trillion in policyholders’ surplus have increased capital allocations for multi-year SaaS core migrations.
| Metric | 2024 | 2025 |
|---|---|---|
| Direct premiums written | USD 1.06 trillion | USD 1.11 trillion (+5%) |
| Net premiums written | USD 863-897 billion | USD 976.8 billion (+4.6%) |
| Net combined ratio | 96.6% | 92.9-93.0% (best in a decade) |
| Net underwriting gain | USD 22.9-23 billion | USD 61.2-63 billion |
| Policyholders’ surplus | USD 1.1 trillion | USD 1.2-1.27 trillion |
2024 vs 2025: DPW $1,060B to $1,110B · NPW $880B to $976.8B · Surplus $1,100B to $1,230B
Net underwriting gain: 2024 $23B · 2025 $62B
Net combined ratio: 2024 96.6% · 2025 93.0%
Key Risk Factors and Migration Challenges
Implementation Complexity and Capital Outlay
Core platform replacements represent high-friction capital expenditures, averaging 18 to 36 months in duration and USD 50 million to USD 300 million in total cost for Tier-1 carriers. Industry historical data indicates that approximately 70% of single-phase “big bang” core replacements exceed budget or fail to meet initial operational metrics, driving carriers to adopt phased, line-of-business migration frameworks.
Data Migration and Legacy Extraction Risk
Extracting, normalizing, and ingesting decades of policy history, loss records, and billing data from legacy mainframes to cloud databases represents up to 40% of total implementation budgets. Fifty percent of carrier IT executives identify legacy data schema incompatibilities as the primary bottleneck in platform deployment.
Cybersecurity Exposure and Regulatory Risk
Insurance sector cyber security incidents increased by 38% between 2022 and 2024 (IBM Security X-Force). Over 92% of CIOs rate cloud security controls as a primary filter during core selection. Under the EU DORA framework, regulators now exercise direct supervision over cloud core platform providers as critical ICT third-party vendors.
COBOL Engineering Deficit
Seventy-two percent of insurance technology executives report talent shortages across cloud architecture and data engineering. With roughly 50% of current legacy mainframe engineering staff reaching retirement age by 2030, maintaining custom legacy code bases is incurring escalating labor premiums.
Core Platform Vendor Landscape & Benchmarks
Enterprise vendor selection turns on ARR growth, cloud architecture maturity, and multi-jurisdiction rate filing compliance. This section benchmarks leading SaaS providers across enterprise and mid-market carrier segments.
Revenue: DXC Insurance $1.5B · Guidewire FY26E $1.44B · Sapiens FY24 $0.54B · Majesco (private)
Guidewire Software
Guidewire Software (NYSE: GWRE) holds an estimated 12.13% share of Tier-1 and Tier-2 enterprise cloud P&C deployments. InsuranceSuite (PolicyCenter, ClaimCenter, BillingCenter) serves 550+ carriers globally. For FY2025 (ended July 2025), Guidewire reported total revenue of USD 1.20 billion (+23% YoY), with ARR exceeding USD 1.0 billion. Total revenue for the second quarter of fiscal year 2026 was $359.1 million, an increase of 24% from the same quarter in fiscal year 2025. As of January 31, 2026, annual recurring revenue, or ARR, was $1,121 million, compared to $1,041 million as of July 31, 2025.
Duck Creek Technologies
Duck Creek Technologies operates as a cloud-native SaaS alternative on Microsoft Azure. Acquired by Vista Equity Partners in March 2023 for USD 2.6 billion, Duck Creek OnDemand processes policy, rating, and claims workflows across 150+ carriers. In April 2026, Duck Creek launched its Agentic AI Platform, incorporating a Model Context Repository to ground generative models in carrier-specific underwriting guidelines.
Sapiens International
Sapiens International (NASDAQ: SPNS) provides core software to 600+ financial institutions across EMEA and North America. Sapiens reported FY2024 revenue of USD 542.4 million, with Q3 2025 revenue reaching USD 152.3 million (+11.2% YoY). In August 2025, Advent International entered into a definitive agreement to acquire Sapiens for USD 2.5 billion ($43.50 per share).
Majesco
Majesco (Thoma Bravo portfolio) serves 350+ insurers across 1,000+ implementations. Majesco’s platforms now process over $100 billion in direct written premium, up from $36 billion in 2024. The company launched 13 AI agents across property and casualty and life and annuity insurance segments.
Regional Analysis
North America
North America represents the primary addressable market for core vendors, encompassing 2,500 P&C carriers (NAIC). U.S. insurance IT expenditure is projected at USD 173 billion in 2026, with 52% of carriers actively executing core replacements and 27% planning initiatives within 12 months.
Europe
European non-life premiums reached USD 480 billion (EIOPA), expanding 5.8% in 2024. The Solvency II Review (2025–2027) and IFRS 17 compliance costs ($50M–$500M per carrier) are driving unified core reporting upgrades. DORA ICT vendor risk rules became fully enforceable in January 2025.
Asia Pacific
Asia Pacific is the fastest-growing regional market, with non-life premiums exceeding USD 700 billion (+7% to +12% annual growth). China leads regional volume at USD 250B+, while India is pursuing IRDAI’s “Insurance for All by 2047” regulatory directive. TrendX Insights projects Asia Pacific will record a regional CAGR of 14.80% through 2034.
South America and Middle East and Africa
South America generated USD 80 billion in P&C premiums (+7.6% YoY), with regional insurtech funding reaching USD 199 million in 2025 (+117% YoY) alongside Brazil’s Open Insurance mandate. Middle East and Africa premiums reached USD 31 billion, led by UAE and Saudi Vision 2030 regulatory shifts.
Cloud-Based P&C Core Platforms
Cloud-native architecture has become the baseline requirement for new core platform selections, expanding from 12% carrier adoption in 2019 to 40% in 2025.
| Year | % Insurers with ≥1 Cloud Core | % New Implementations Cloud |
|---|---|---|
| 2019 | 12% | 35% |
| 2021 | 20% | 55% |
| 2023 | 30% | 70% |
| 2025 | 38-42% | 80%+ |
| 2027 (projected) | 60-65% | 90%+ |
Cloud adoption: Insurers with cloud 12% to 40% to 62% · New implementations 35% to 80% to 90%
- Total cost of ownership: 20-40% reduction over five years
- Time to market for new products: 50-70% faster
- System scalability: 30-50% improvement
- Release frequency: shift from quarterly/annual to continuous deployment
- IT operations overhead: 40-60% reduction
AI & Automation Deployment Metrics
Artificial intelligence has transitioned from exploratory testing into targeted production workflows across policy administration and claims adjudication. However, deployment depth varies significantly across functional areas.
| Functional Area | Deployment Status & Metrics |
|---|---|
| Generative AI Evaluation | 90% of carriers evaluating or piloting LLM capabilities; 55% in early production deployment |
| Claims Processing AI | 23% of carriers running production AI claims adjudication; 82% utilizing AI for FNOL triage |
| Underwriting Risk Scoring | 45% of personal lines carriers running production AI risk models; 14% fully automated in commercial lines |
| Operations & Executive Outlook | 70% of insurance IT leaders report active AI in live operations; 52% report measurable ROI |
AI Adoption: GenAI Journey 90% · ML 74% · Claims Production 23% · Underwriting 14% · STP Claims 31% · Consumer Comfort 39%
AI in Claims
Automated triage AI models sort and route incoming claims with 90-95% accuracy. Document processing sees 50-70% reduction in manual data entry time. Computer vision damage assessment operates within 5% of adjuster accuracy. Claims leakage reduction through AI-driven detection saves an estimated 3-5% of total claims costs. Generative AI summaries reduce adjuster administrative time by 25-40%.
AI in Underwriting and Fraud Detection
Machine learning risk-scoring models analyzing hundreds of data points deliver 20-30 percent improvement in loss ratio accuracy, and 40-50 percent of personal lines submissions are handled without human intervention at leading carriers. AI-powered fraud detection identifies 40-60 percent more fraudulent claims than rule-based systems; Shift Technology alone processes over 400 million claims globally.
Regulatory Watch: AI Governance
As of early 2026, 23-26+ US states and Washington, D.C. have adopted some form of the NAIC Model Bulletin on AI, requiring carriers to maintain written AI governance programs, document model testing, and conduct third-party AI vendor due diligence. Over 90% of insurers report having regularly revised AI governance policies, but fewer than 30% believe that is enough to keep pace with shifting regulatory demands.
Enterprise Modernization Case Studies
Liberty Mutual: Serverless Financial Architecture
Liberty Mutual migrated its core financial transaction engine to an AWS serverless architecture. The system processes over 100 million monthly financial transactions at an execution cost of $0.00006 per transaction, reducing microservice deployment timelines from 12 months to 3 months.
Zurich Insurance Group: Global Cloud Foundation
Zurich Insurance Group migrated 1,000 application workloads to AWS under its Global Cloud Foundation program, achieving a 97% data center reduction across Zurich North America and reducing environment provisioning times from 48 hours to 2 hours.
State Farm: Mainframe Migration & DevOps
State Farm modernized 800 legacy applications using AWS Mainframe Modernization and VMware Tanzu, compressing deployment cycles from multi-week release windows to automated daily releases.
USAA: Data Warehousing Optimization
USAA unified its financial reporting infrastructure on Snowflake and Oracle Cloud, achieving a 51% reduction in monthly book-closing cycle times and eliminating 27% of manual audit controls.
Future Outlook: 2026 to 2035
Embedded Insurance
Embedded insurance, sold through non-insurance platforms at the point of sale, is one of the most transformative trends for core platforms. By 2030, an estimated 30 to 35 percent of new P&C premiums could originate through embedded channels, with key distribution via e-commerce, fintech apps, travel booking, automotive OEMs, and gig economy platforms. Publicly available insurance APIs have grown from roughly 200 in 2020 to over 1,000 by 2025.
Composable Architecture
The industry is moving from monolithic systems toward composable, modular designs following MACH principles. By 2028, an estimated 40-50 percent of core platform implementations are expected to follow composable architecture principles.
Autonomous Claims Processing
| Year | Estimated STP Rate (All Types) | Personal Lines STP |
|---|---|---|
| 2024 | 25-35% | 40-60% |
| 2028 (projected) | 45-55% | 60-70% |
| 2030 (projected) | 70-90% (simple claims) | 80%+ |
| 2035 (projected) | 80%+ (simple claims) | 90%+ |
AI Evolution: Three Phases
- Assistive AI (2024-2026): Generative AI tools that summarize documents, draft communications, and recommend actions for human review
- Co-pilot AI (2026-2028): AI systems that actively collaborate with underwriters and adjusters, making preliminary decisions subject to human oversight
- Autonomous AI (2028-2035): Agentic AI systems making binding decisions for standard risks and routine claims without human intervention
Key Takeaways
P&C Core Platform Market: Key Numbers at a Glance
Frequently Asked Questions
TrendX Insights values the global P&C Core Insurance Market at USD 9.45 billion in 2025, expanding to USD 21.21 billion by 2034 at a 9.40% CAGR. North America accounts for 54.6% of current revenue, while Asia-Pacific is projected to record the highest growth at a 14.80% CAGR.
Guidewire Software, Duck Creek Technologies, Sapiens International, and Majesco command over 60% of Tier-1 and Tier-2 enterprise contracts. Guidewire leads total revenue ($1.20B in FY2025, with FY2026 ARR guidance raised to $1.229-1.237B).
An estimated 60% to 74% of P&C carriers still operate legacy policy administration systems, with maintenance fees absorbing 50% to 80% of total carrier technology expenditure.
Tier-1 core replacements average USD 50 million to USD 300 million in total cost over an 18 to 36 month deployment window. Single-phase ‘big bang’ migrations exhibit a 70% budget overage rate, driving adoption of modular microservices.
AI deployment remains functional but targeted. While 90% of carriers report piloting LLM applications, end-to-end autonomous claims adjudication is currently active across only 23% of carriers, primarily in high-frequency auto claims.
Cloud SaaS accounts for over 80% of new core selections, driven by 20% to 40% reductions in 5-year total cost of ownership, 50% to 70% faster time-to-market for new line-of-business launches, and DORA regulatory compliance.
Embedded point-of-sale insurance originations are projected to reach USD 70 billion in U.S. premiums and USD 722 billion globally by 2030, requiring sub-second REST API integration from core policy engines.
Asia Pacific is projected to record the highest regional growth rate at 14.80% CAGR through 2034, driven by regulatory liberalization in India and rapid digital carrier expansion across Southeast Asia.
U.S. P&C insurers generated USD 1.11 trillion in direct premiums written (+5% YoY) and USD 61.2 billion in net underwriting gain, lowering the net combined ratio to 92.9% (a 10-year operational benchmark).
Twenty-six U.S. jurisdictions have adopted the NAIC Model Bulletin on AI, requiring formal governance and model testing documentation. In Europe, DORA regulates cloud platform vendors as critical third-party ICT infrastructure.
- NAIC – U.S. Property & Casualty and Title Insurance Industries, 2025 Full Year Results
- AM Best – 2025 US P/C Industry Results and Rankings
- Verisk / APCIA – Strong 2025 Underwriting Income Analysis
- ACORD – 2025 Digital Maturity Study
- Gartner – Magic Quadrant for SaaS P&C Insurance Core Platforms, North America, September 2025
- Guidewire Software – Q2 Fiscal Year 2026 Financial Results, March 2026
- Duck Creek Technologies – Agentic AI Platform launch and Gartner MQ recognition, 2025-2026
- Sapiens International – FY2024/2025 results and Advent International acquisition, December 2025
- Majesco – 2025 Gartner MQ recognition and Fall 2025 product release
- OECD – Global Insurance Market Trends 2025
- Swiss Re Institute – sigma research: “Growing stronger: P&C market adapts to a riskier world” (Sept. 2025)
- EIOPA – Financial Stability Report 2024
- TrendX Insights – P&C Core Insurance Market syndicated report
- Deloitte – 2026 Insurance Industry Outlook
- McKinsey & Company – Generative AI in insurance research, 2026
- Geneva Association – Global insured catastrophe loss estimates
- IBM Security X-Force – Threat Intelligence Index, insurance sector cyberattack trends
- J.D. Power – 2024 U.S. Property Claims Satisfaction Study
All figures are sourced from publicly available government databases, peer-reviewed research, industry association publications, company investor disclosures, and TrendX Insights’ own syndicated market research, dated 2024-2026. Where ranges are given, the underlying sources are cited. TrendX Insights does not accept payment from any vendor to influence research findings. This content is for informational purposes only and does not constitute investment advice.
Have a question, correction, or additional data point? Our research team reads every submission. Data errors or source disputes receive priority responses.